

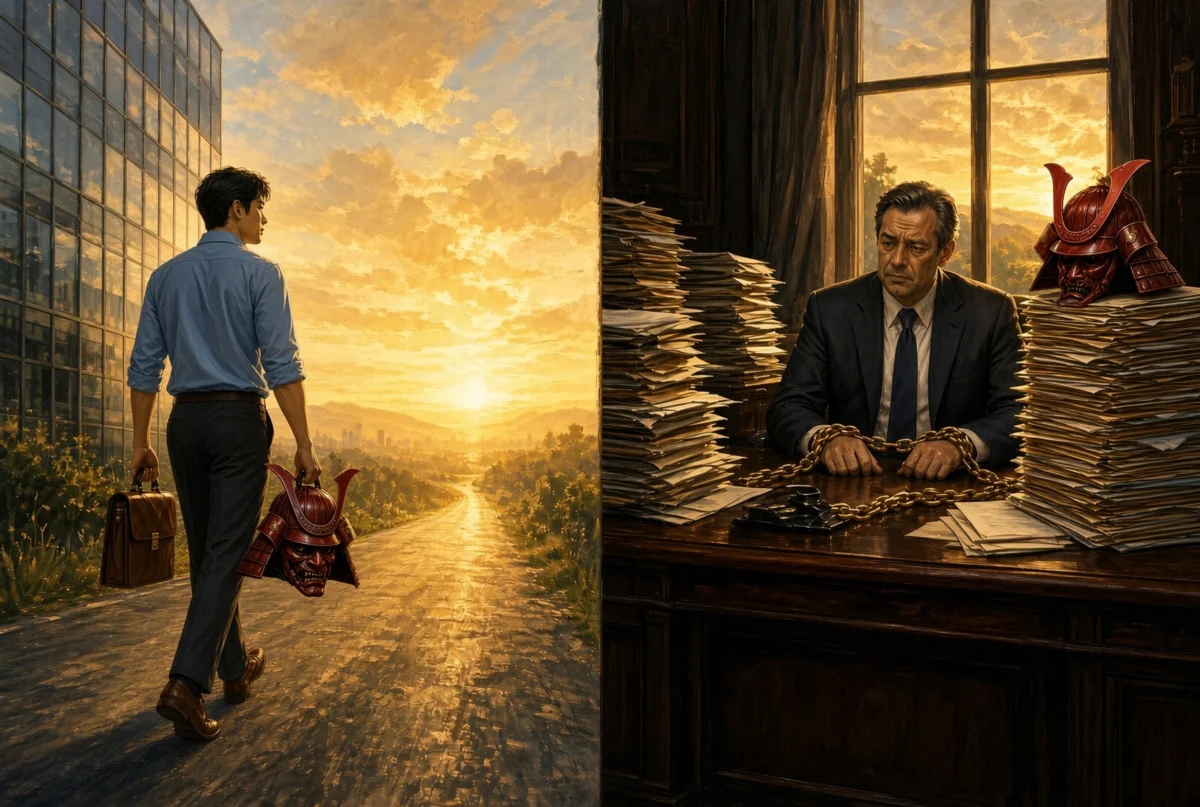
The concept of Financial Independence, Retire Early (FIRE) has long been framed as a mathematical equation: accumulate enough assets to sustain a lifestyle through passive income, and the labor market becomes optional. However, as the movement matures, longitudinal analysis suggests that the "timing" of this transition is the most critical variable. While conventional wisdom suggests that retiring later, with more wealth and experience, provides a safer foundation, emerging evidence indicates that the psychological and economic barriers to retirement grow exponentially as one ages, often making the jump significantly harder at 50 than at 35.
The Economic Paradox of High-Earner Attrition
In 2012, a significant shift in career trajectory occurred for many professionals in high-stakes industries like investment banking and technology. Data from the era shows a cohort of professionals reaching their mid-30s—a point where earning power typically begins to compound aggressively—who chose to pivot away from corporate life. For these individuals, the decision was predicated on the assumption that they could always return to the labor market if their early retirement experiment failed.
This "reversibility" is the primary advantage of early retirement. At 35, the opportunity cost of a failed retirement is often limited to a two-to-three-year gap in a resume. Conversely, for a 50-year-old executive or high-level specialist, the stakes are markedly different. A professional in their fifth decade of life typically commands a salary bracket that carries with it significant deferred compensation, stock options, and the weight of "golden handcuffs." Walking away from a position that might yield $500,000 in base salary and a multi-million dollar performance bonus is a fiscal decision that carries the risk of permanent income loss, as ageism in the professional sector often makes re-entry into high-level roles difficult.
Chronology of Career Risk and Lifecycle Obligations
The trajectory of personal finance responsibilities follows a predictable, yet often underestimated, timeline. A 35-year-old professional is frequently unencumbered by the major fiscal obligations that define the later stages of mid-life.
- Age 22–30: The accumulation phase, characterized by aggressive saving and minimal dependents.
- Age 30–35: The "Leap Phase," where the potential for FIRE is highest due to lower lifestyle inflation and fewer familial demands.
- Age 40–50: The "Complexity Phase," marked by the peak of private education costs, eldercare responsibilities, and the psychological weight of maintaining a high-net-worth lifestyle.
By age 50, many individuals have fully baked their expenses into a high-cost structure. The transition from a single-earner or dual-earner household to one relying entirely on portfolio distributions creates a rigid financial architecture. If that architecture fails, the ability to "reboot" at 50 is hampered by a job market that increasingly favors younger, lower-cost talent, or requires specialized skill sets that may have evolved during the retiree’s hiatus.
Supporting Data: The Impact of Lifestyle Inflation
Economic research into lifestyle inflation highlights that consumption habits tend to rise in lockstep with income. For a professional who has spent a decade in a high-earning bracket, the "cost of maintenance"—which includes private school tuition, residential real estate taxes, and support staff—creates a financial baseline that is difficult to support without a consistent, high-level W-2 income.
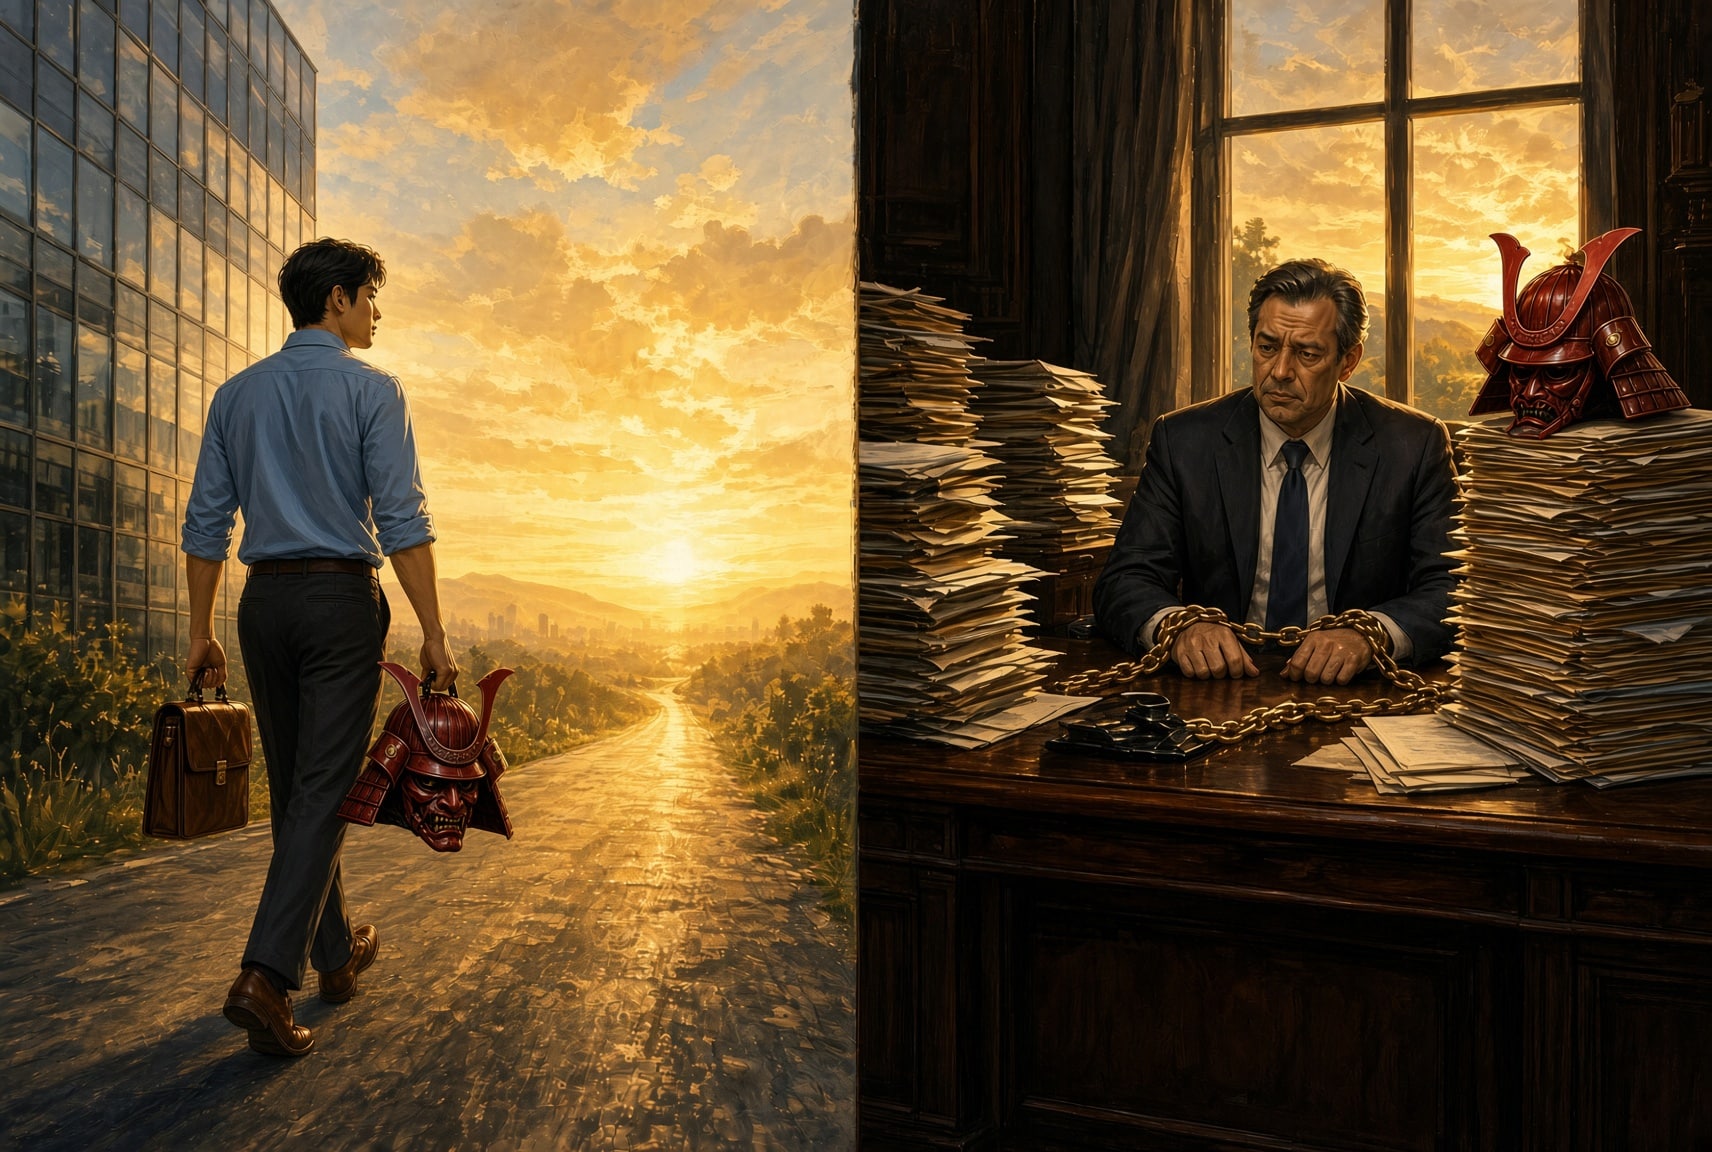
Financial planners note that while a 35-year-old may require a relatively modest sum to cover their living expenses, a 50-year-old with a family, a mortgage on a primary residence, and looming tuition costs needs a significantly larger "FIRE number." This forces a binary choice: either accumulate an insurmountable amount of capital or remain in the workforce far longer than originally intended. The fear of depleting assets during a market downturn, combined with the lack of a safety net in the form of future salary, creates a psychological barrier that often keeps individuals in the workforce well into their 60s, effectively transforming "early retirement" into "standard retirement."
The Role of Technological Displacement
A significant factor that distinguishes the current labor market from that of the early 2010s is the rapid acceleration of artificial intelligence and its impact on knowledge work. In previous decades, a mid-career professional could rely on their institutional knowledge and network to secure a position after a short break. Today, the compression of demand for traditional middle-to-upper management roles has made the professional landscape more volatile.
For the 50-year-old retiree, the risk is not just the loss of income, but the risk of total exclusion from the workforce. The "boats are burned" scenario, once considered a manageable risk, now carries existential weight. Consequently, many high-earners are choosing to stay in their roles not out of a desire to work, but out of a defensive strategy to preserve their economic standing in an uncertain future.
Structural Implications for Retirement Strategy
The implications for those planning their financial futures are clear: the window for a low-risk exit is smaller than commonly perceived. The traditional model of "grind until you’re wealthy enough" is being challenged by the reality of "grind until you’re too old to be hired."
- The Sabbatical Test: Experts increasingly recommend that high-earners utilize long-form sabbaticals—often lasting three to six months—to assess the feasibility of their retirement plans before making a permanent exit. This period serves as a stress test for both the budget and the individual’s psychological readiness.
- Severance Negotiation: Rather than resigning, many professionals are utilizing "engineered layoffs." By negotiating a severance package, an individual can secure a period of financial runway that allows for a transition out of the workforce with a safety net, potentially bridging the gap to a new career or full retirement.
- The Generational Wealth Conflict: The desire to provide for future generations often conflicts with the desire for personal freedom. Parents must navigate the balance between retiring early and ensuring their children are insulated from an increasingly expensive economic environment.
Conclusion: The Psychology of the Leap
Ultimately, the decision to retire is rarely purely mathematical. It is a psychological negotiation between the comfort of the status quo and the desire for autonomy. The evidence suggests that the "safe" path—waiting until 50 to ensure maximum financial security—is often a mirage, as the external and internal costs of continuing to work rise alongside one’s net worth.
For those who prioritize autonomy, the data indicates that the risk of failure is significantly more manageable at 35 than at 50. The ability to recover, the lower baseline of essential expenses, and the greater flexibility of the younger labor market all contribute to a higher probability of success. In contrast, retiring at 50 is a high-stakes maneuver that requires not only significant capital but a willingness to accept that the path back to the corporate world may be permanently closed. The most effective time to pursue independence, therefore, appears to be the moment the transition feels most daunting, rather than waiting for a level of certainty that may never arrive.
