

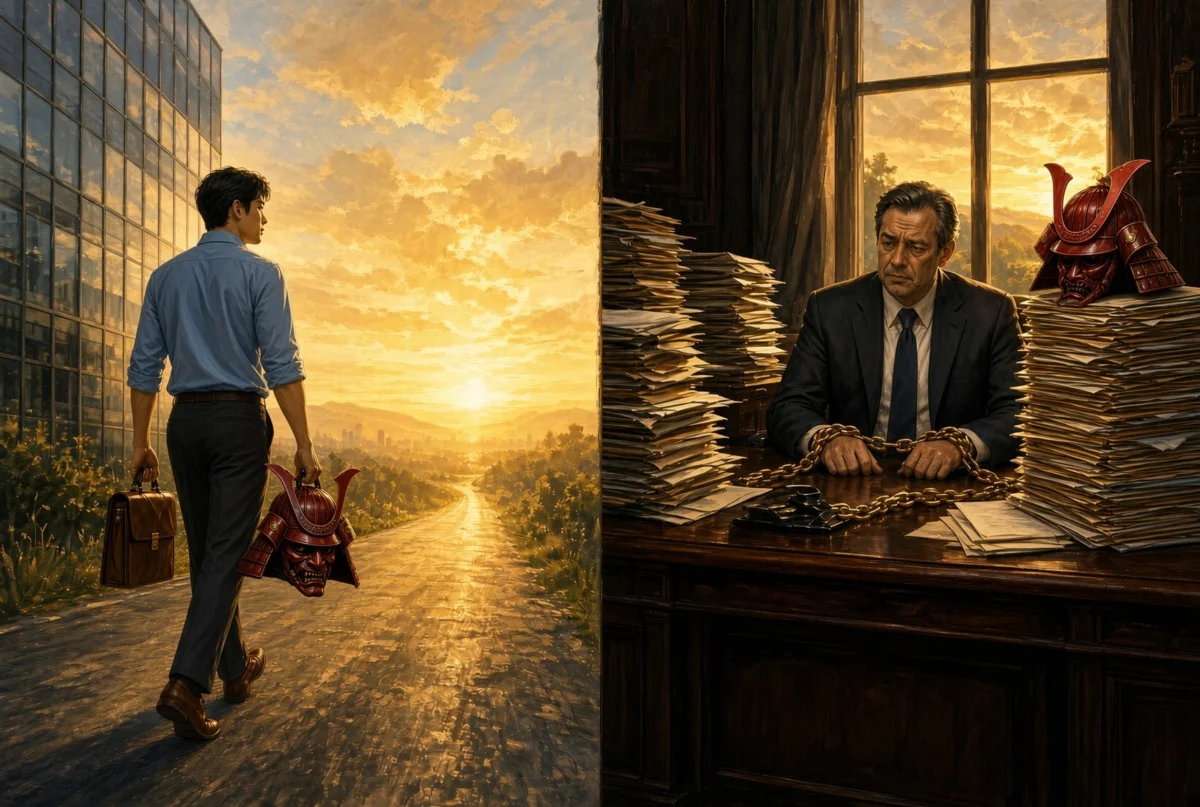
The concept of Financial Independence, Retire Early (FIRE) has evolved from a niche subculture into a significant economic phenomenon, yet many professionals operate under the misconception that the pursuit becomes easier as one ages and accumulates wealth. Recent analysis of labor trends and wealth management data suggests the inverse: the "golden handcuffs" of high-earning corporate roles, lifestyle inflation, and increased familial obligations create a structural barrier that makes retiring at 50 significantly more difficult than at 35.
The Dynamics of Early Retirement: A Longitudinal Perspective
The decision to exit the workforce at 35 is frequently characterized as a period of high-risk, high-reward maneuvering. In 2012, many professionals in the financial sector began testing this hypothesis, choosing to depart long-term banking careers. At that life stage, the individual is typically unencumbered by the high-cost maintenance of children, private education, and the complex logistical requirements of elder care.
Chronologically, the window between age 30 and 40 represents a unique period where an individual’s professional earning potential has begun to scale, but their personal liabilities have not yet fully crystallized. Conversely, reaching age 50 often coincides with the peak of one’s career trajectory—such as reaching a Managing Director level in investment banking—where total compensation, including deferred bonuses and stock options, can exceed $2 million annually. The economic cost of walking away from this compensation, adjusted for inflation and the loss of future compounded gains, presents a psychological and financial hurdle that few are prepared to clear.
Comparative Risk Analysis: Age 35 vs. Age 50
Data regarding the labor market suggests that the "re-entry" risk—the probability of successfully returning to the workforce after a hiatus—is significantly lower for a 35-year-old than for a 50-year-old.
- Marketability: A 35-year-old professional typically possesses skills that are still considered current and highly relevant. In contrast, those aged 50 face age-related bias and a job market increasingly disrupted by artificial intelligence and automation, which prioritize lower-cost, high-efficiency output over the high-level, expensive management experience often associated with older cohorts.
- Lifestyle Inflation: By age 50, most high earners have built a "lifestyle architecture" that requires a substantial, consistent cash flow. This includes mortgage obligations on larger properties, private school tuitions that can range from $40,000 to $60,000 per child annually, and a reliance on domestic support staff. The pressure to maintain this standard of living acts as a tether, effectively preventing the individual from voluntarily exiting the workforce.
- The "Burned Boat" Scenario: For a 35-year-old, retirement is often a reversible experiment. If the transition fails, the individual can usually secure a new position within 12 to 18 months. For a 50-year-old, the exit is often terminal; the lack of viable employment options means the decision must be backed by a fully realized, inflation-protected financial independence plan that covers at least three decades of longevity.
The Role of Severance and Exit Strategy
A critical component of successful early retirement, particularly for those in high-stress industries, is the strategic negotiation of a departure. Rather than a traditional resignation, which forfeits potential severance packages, many professionals now utilize "engineered layoffs." By documenting performance, negotiating mutually beneficial exits, and securing deferred compensation, individuals can create a financial runway that bridges the gap between full-time employment and full independence.
Financial advisors note that the success of this strategy is highly dependent on the "runway" created. In 2012, a severance package might have provided a sufficient buffer for a few years, but in the current economic climate—characterized by higher volatility and inflationary pressure—the required capital to sustain early retirement has increased.

Societal and Familial Implications
The desire to build multi-generational wealth adds a layer of complexity that was absent for the previous generation of retirees. Modern parents, particularly those in high-earning brackets, feel an increased obligation to fund not just undergraduate education but also to provide a financial cushion for their children to navigate a future economy marked by higher entry-level barriers.
This leads to the "grind paradox": the more successful an individual is at earning, the more they feel compelled to continue working to ensure their children’s security. This observation is supported by the increasing trend of "stay-at-home" partners, where one parent manages the domestic sphere to allow the other to focus exclusively on maximizing W-2 income. This arrangement, while effective for short-term wealth accumulation, creates a dependency loop that makes exiting the workforce even more precarious for the primary earner.
Data Trends and Economic Realities
Economists observing the FIRE movement emphasize that the "best time" to achieve independence is often when it feels most uncomfortable. Waiting for the "perfect" moment—characterized by total financial certainty—often results in the individual remaining in the workforce until traditional retirement age.
- Compounding Factors: The 13-year span after college (age 22 to 35) is arguably the most efficient time to save. By investing over 50% of income during this period, individuals can leverage the power of compound interest for the longest possible duration.
- The Cost of Delay: Delaying retirement from 35 to 40 or 45 often increases the "cost" of retirement due to the aforementioned lifestyle inflation. The transition at 50 is rarely a result of having "enough," but rather a forced exit due to burnout or organizational restructuring, which often lacks the proactive planning necessary for a successful transition to non-work life.
Conclusion: The Strategic Window
The evidence suggests that the window for achieving FIRE is narrower than commonly believed. While age 50 offers a larger absolute amount of capital, the "emotional and structural" costs associated with that age often outweigh the financial benefits.
Industry analysts advise that those considering an exit should conduct a "sabbatical test" rather than a permanent retirement. A two-to-three-month hiatus from the workforce provides a realistic look at the psychological and financial demands of life without a W-2 income. This trial period serves as a diagnostic tool to determine whether the individual is prepared for the shift from active earning to capital preservation.
Ultimately, the decision to retire early is less about the total sum in a portfolio and more about the individual’s ability to manage their own "lifestyle inflation." For those who can maintain a modest standard of living, the path to independence at 35 remains a viable, albeit challenging, strategy. For those who wait until 50, the journey requires not just a large nest egg, but the courage to dismantle a complex, high-maintenance lifestyle that has likely taken decades to construct. The primary takeaway for professionals is clear: the risk of failure is lower when you have less to lose, and the regenerative capacity of a younger professional is a significant asset that should not be overlooked in the long-term financial planning process.
