

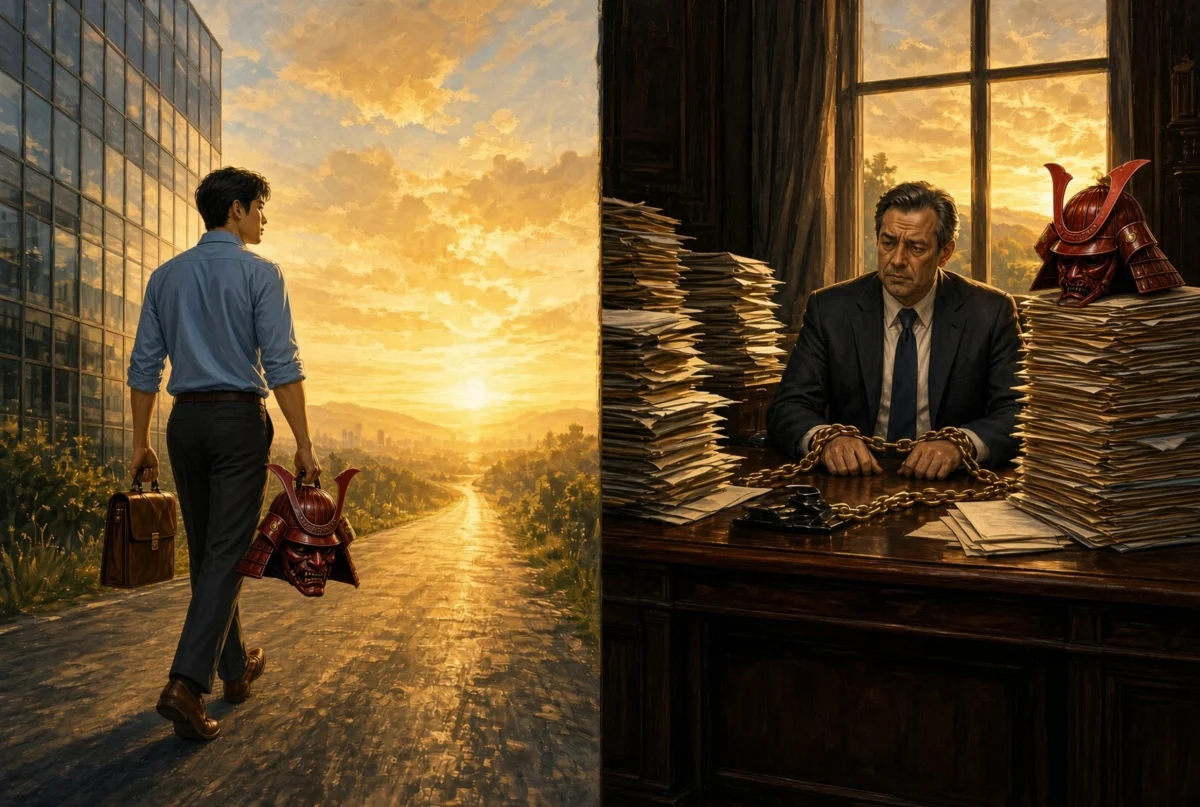
The concept of Financial Independence, Retire Early (FIRE) has evolved from a niche subculture into a significant economic consideration for high-earning professionals. While conventional financial planning often suggests that retiring later allows for greater asset accumulation and increased security, current labor market dynamics and behavioral economics suggest that the risks of early retirement are often inversely proportional to age. Data indicates that individuals who choose to exit the workforce in their mid-30s face significantly lower barriers to re-entry and fewer systemic financial obligations than those who attempt a similar transition at age 50.
The Chronology of Career Departure
In 2012, a significant trend began to emerge among professionals in high-stress sectors, such as investment banking and big tech, characterized by the proactive termination of high-earning roles. For many, this decision was not prompted by a lack of capital, but by a strategic reassessment of long-term utility versus quality of life.
The decision-making process at age 35 often differs fundamentally from the calculus applied at 50. At 35, many professionals possess limited domestic obligations, such as the absence of dependents or significant elder-care responsibilities. This lack of "lifestyle inflation" serves as a critical buffer. By the age of 50, however, professional compensation often reaches its peak, leading to expanded fixed costs—private education, luxury real estate, and extensive household management—that create a state of financial dependency on high-level income.
Comparative Risk Analysis: Mid-30s vs. Mid-50s
An objective analysis of labor market statistics reveals that the "golden handcuffs" of corporate employment tighten over time. At 35, an individual typically retains high professional mobility. Should a departure from the workforce fail to yield the desired lifestyle results, the window for re-entry into the labor market remains wide, with potential employers often viewing a 12-to-24-month gap as a manageable sabbatical or entrepreneurial endeavor.
Conversely, the job market for those approaching 50 is markedly more rigid. Data from the Bureau of Labor Statistics and various human capital reports consistently highlight the prevalence of age-related bias in recruitment for senior-level roles. Furthermore, the integration of Artificial Intelligence and automation into the knowledge-work sector has compressed the demand for mid-to-senior level managers. A 50-year-old professional exiting the workforce must account for the reality that their specific skill set may be subject to technological displacement, making a return to a high-earning capacity statistically improbable.
Financial and Social Implications
The financial stakes between these two life stages are distinct. At 35, the primary risk is the loss of a decade of compound growth on savings. At 50, the risk shifts to the depletion of capital reserves during a period where market volatility and inflation can significantly diminish purchasing power.

Moreover, social and familial responsibilities act as a primary deterrent for older professionals. As of 2024, the cost of higher education and the potential for multi-generational wealth transfer have become central pillars of the late-career financial plan. For many, the transition to retirement at 50 is not merely a personal choice but a negotiation with the economic future of their children. This creates a psychological barrier; the professional is no longer working solely for personal freedom, but to ensure the financial viability of their dependents in an increasingly competitive economy.
Structural Barriers to Late-Stage Exit
When evaluating the feasibility of retiring at 50, the following factors demonstrate why the exit strategy becomes inherently more difficult:
- Compounding Compensation: By age 50, many professionals have reached the level of Managing Director or equivalent, where base salaries are supplemented by substantial discretionary bonuses. Walking away from a total compensation package that may exceed $2 million annually creates a high threshold for "financial regret."
- Fixed Lifestyle Costs: The transition from a modest lifestyle to a high-expenditure life is often irreversible. Reducing a household budget that includes private schooling and multiple property maintenance costs is psychologically and socially difficult.
- The Erosion of Re-hireability: In the current economic climate, the labor market favors agility and lower-cost, high-output younger talent. A gap in a resume at age 50 is frequently interpreted by hiring managers as a signal of obsolescence or a lack of institutional commitment.
Economic Observations on the "Quit vs. Layoff" Dynamic
A recurring theme in the FIRE community is the distinction between voluntary resignation and the negotiation of a severance package. Financial analysts note that the latter is a far more robust strategy for exiting a role. By "engineering a layoff," employees often retain access to unemployment benefits, accrued deferred compensation, and, in some cases, outplacement services.
This approach serves as a critical bridge. In the 2012 example, the availability of a negotiated severance provided the necessary liquidity to manage the transition without immediate pressure to generate active income. This highlights a broader economic truth: the transition to retirement is rarely a singular event, but a managed exit that requires the same level of strategic planning as a corporate merger or acquisition.
Future Outlook and Strategic Recommendations
The evidence suggests that the "optimal" window for financial independence is narrower than previously assumed. Younger professionals have the advantage of time to recover from strategic errors, while older professionals are constrained by the sheer momentum of their careers and the weight of their financial commitments.
For those currently in their late 40s considering a departure, the following considerations are essential for long-term viability:
- The Sabbatical Test: Before making a permanent exit, professionals are advised to utilize a formal leave of absence or a paid sabbatical. This allows for a realistic assessment of life without the structure of a W-2 income, providing a risk-free environment to test one’s psychological readiness for retirement.
- The "Burn the Boats" Threshold: Retirement at 50 requires a level of certainty that is rarely achieved in the private sector. Individuals must calculate their withdrawal rates based on conservative market projections, accounting for the possibility that they will never receive another W-2 paycheck.
- Generational Wealth vs. Personal Freedom: Individuals must reconcile the trade-off between early retirement and the ability to fund future educational or capital needs for their children. The pursuit of personal freedom must be weighed against the potential impact on familial economic stability.
Ultimately, the data suggests that the most effective time to seek independence is when the fear of remaining in the current role outweighs the fear of the unknown. As the global economy continues to shift toward more automated, less stable employment models, the traditional path of "working until retirement age" is being replaced by a more fragmented, individualistic approach. However, this shift remains heavily dependent on the age at which one begins the transition, as the flexibility of the labor market diminishes in direct proportion to one’s years of service.
