

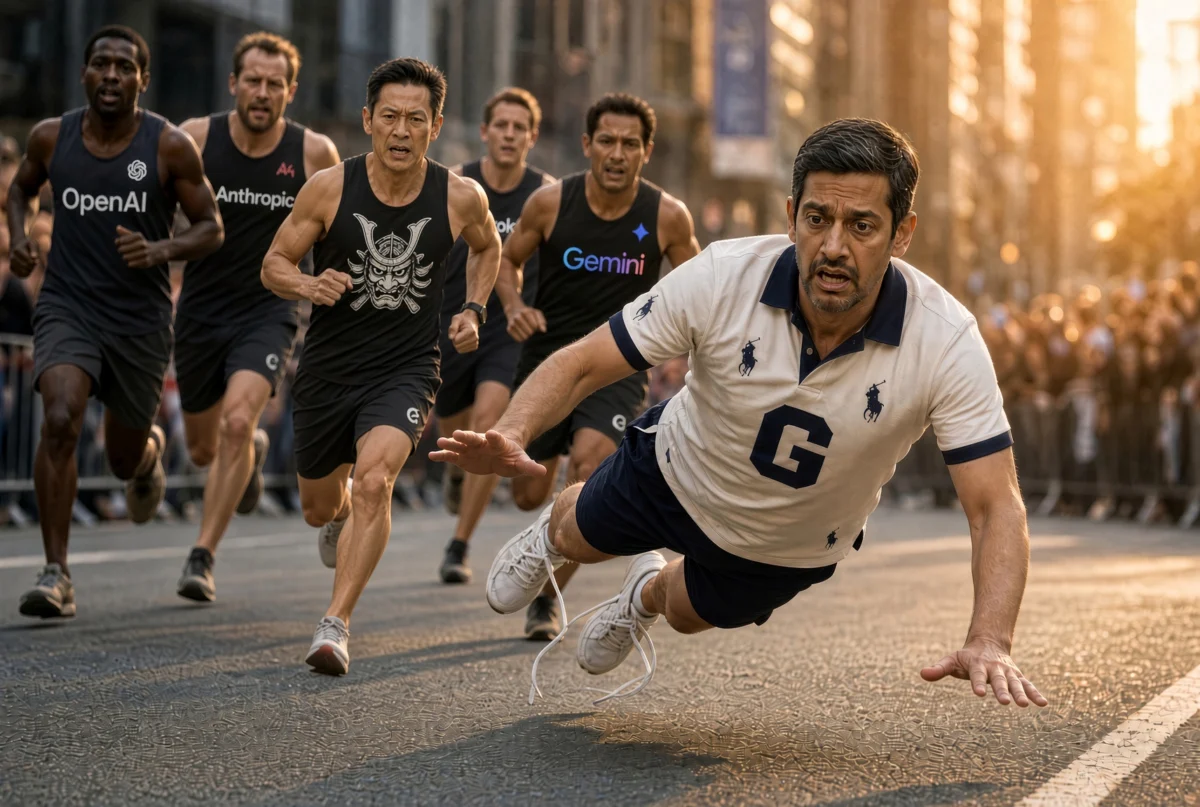
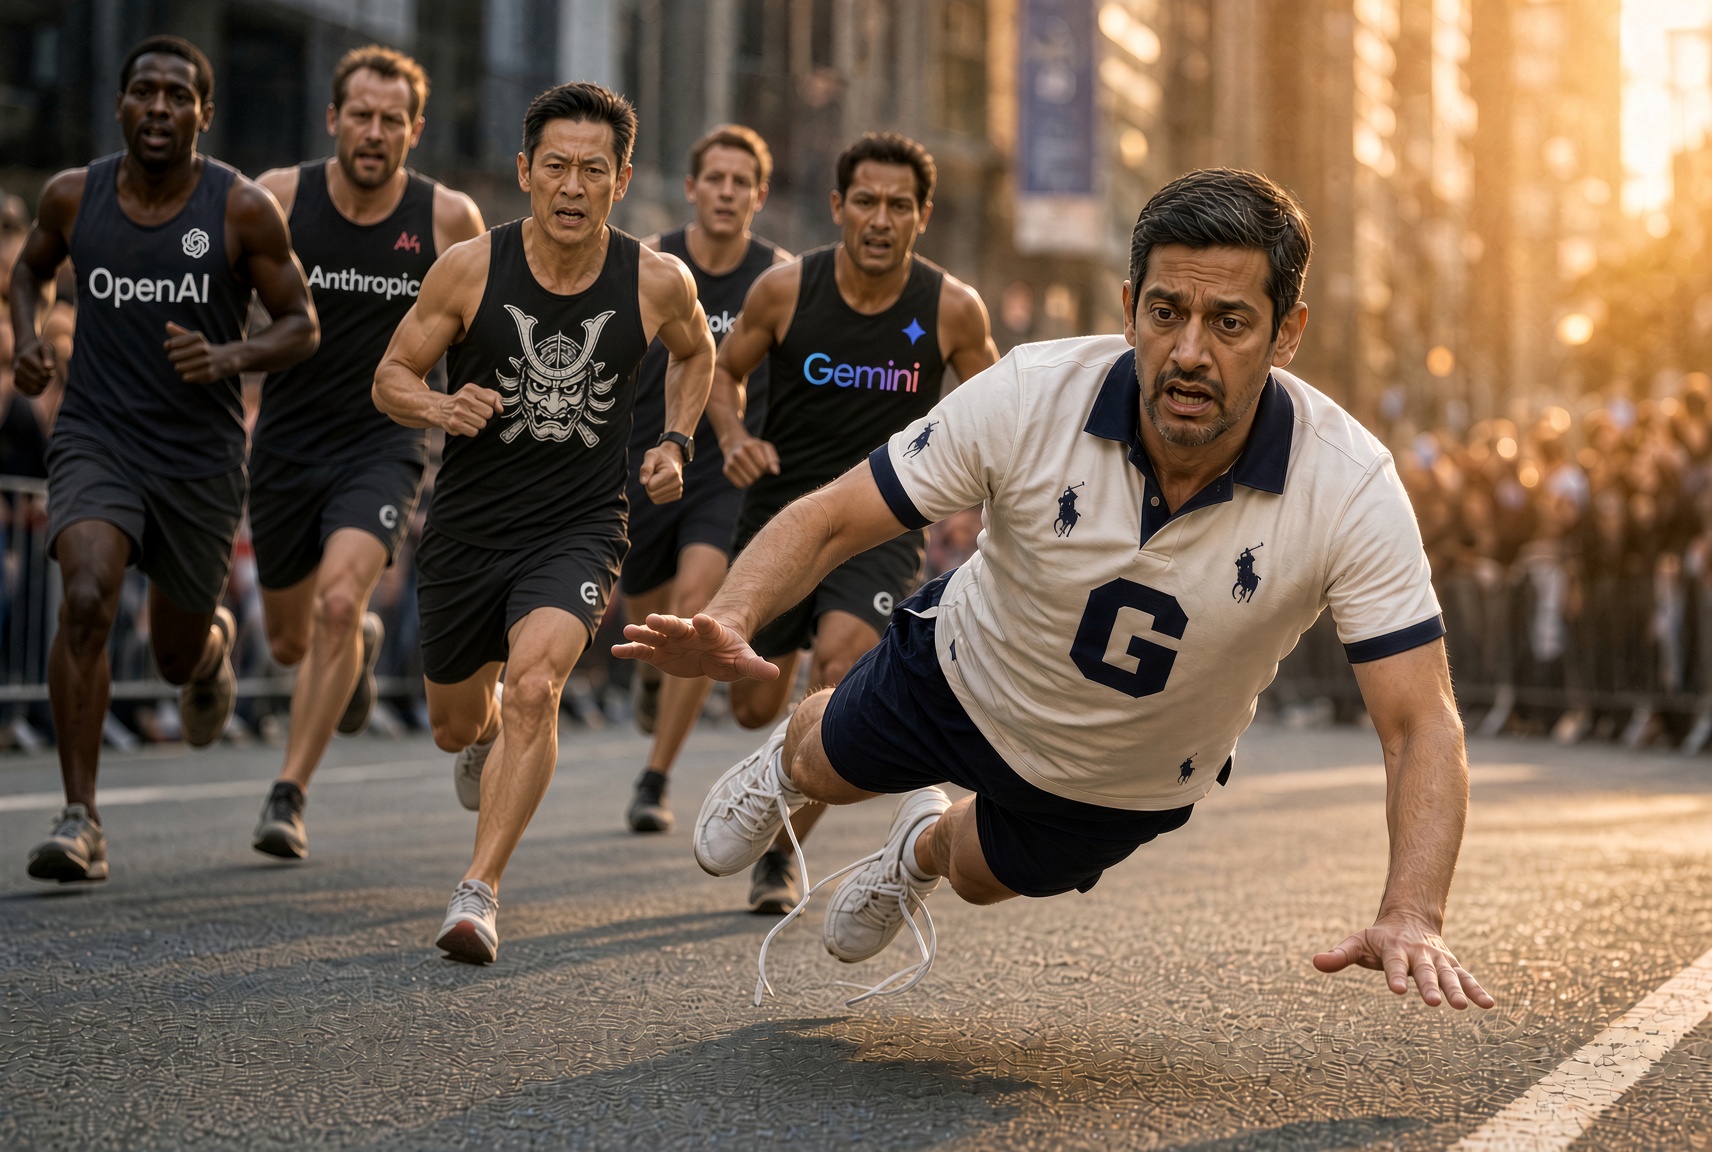
Alphabet Inc., the parent company of Google, finds itself at a critical juncture following a stark quarterly earnings report that triggered a 12% decline in its stock price. The sell-off reflects growing investor anxiety regarding the firm’s massive capital allocation toward artificial intelligence and its perceived failure to maintain its historical lead in the sector. Despite being the pioneer of the transformer architecture—the foundational technology behind modern large language models—Google is currently navigating a competitive landscape where smaller, more agile firms appear to be capturing significant developer mindshare.
A Chronology of the AI Arms Race
To understand the current state of Google’s search and AI business, one must look back to 2017, the year Google Brain researchers published the seminal paper, "Attention Is All You Need." This research introduced the Transformer, a deep learning model that became the bedrock for generative AI tools like OpenAI’s ChatGPT. At the time, Google possessed a unique trifecta: the world’s most powerful search index, a massive proprietary cloud infrastructure, and an internal hardware division designing Tensor Processing Units (TPUs) specifically for machine learning workloads.
By 2022, however, the narrative shifted. With the public release of ChatGPT, OpenAI—backed by billions in Microsoft funding—demonstrated that Google’s research could be commoditized and integrated into consumer-facing products at a speed that caught the incumbent off guard. Throughout 2023 and 2024, Google pivoted aggressively, launching Gemini and integrating AI Overviews into its search results. Despite these efforts, the company’s internal metrics and external market share data suggest that the "first-mover advantage" in research did not translate into a dominant commercial position in the generative AI application layer.
The Financial Burden of Catch-Up
The primary concern among institutional investors is the sheer scale of capital expenditure (CAPEX). Alphabet reported that it is currently deploying approximately $200 billion in infrastructure spending annually to bolster its data centers and GPU capacity. This figure represents an extraordinary level of investment, surpassing the total GDP of many sovereign nations.
The financial strain is evident in the company’s cash flow statements. For the most recent quarter, Alphabet reported a negative free cash flow of $9 billion, a stark departure from its historical profile as a self-sustaining cash machine. Market analysts note that while such spending is intended to secure long-term cloud and AI dominance, the return on invested capital (ROIC) remains elusive. Critics argue that this aggressive spending reflects a "defensive" strategy—an attempt to preserve the search monopoly against disruption rather than a proactive expansion into new, profitable frontiers.
Developer Ecosystem and Competitive Dynamics
While Google maintains a massive user base across Android, Chrome, and Gmail, its standing among the developer community has faced headwinds. Modern software development is increasingly centered around API ecosystems provided by OpenAI, Anthropic, and open-source models hosted on platforms like Hugging Face.
Industry reports suggest that many enterprise developers prefer Anthropic’s Claude or Meta’s Llama models for specific coding and reasoning tasks. This fragmentation of the developer ecosystem poses a long-term risk to Google’s Cloud Platform (GCP). If developers build their applications on competing models, Google’s ability to monetize these workflows through its cloud services diminishes. The company is effectively in a position where it must subsidize its own infrastructure while watching the intellectual output of the AI revolution migrate toward external competitors.
The Conflict Between Publishers and AI Search
A significant, often overlooked dimension of Google’s current crisis is its strained relationship with the digital publishing ecosystem. For two decades, Google functioned as an engine of discovery, driving traffic to millions of independent websites, blogs, and news outlets. In exchange, Google monetized that traffic through its dominant advertising stack.
The transition to AI Overviews—which summarize content directly on the results page—has disrupted this symbiotic model. Publishers argue that this "zero-click" search experience cannibalizes their traffic, potentially eroding the very data sources Google needs to train its future models. This has led to a flurry of lawsuits and licensing negotiations between tech platforms and media organizations, creating a regulatory and legal landscape that adds further complexity to Google’s operational path forward.
Implications of Organizational Culture
The internal culture of Google, famously characterized by its "20% time" and academic research environment, is now under the microscope. In the technology sector, the phrase "rest and vest" has become shorthand for a culture that critics describe as bloated and risk-averse. While the company maintains an exceptionally high talent density, the bureaucratic hurdles inherent in a company of its size often impede the "ship-it-fast" mentality that has allowed startups to leapfrog established tech giants.
Observers point to the success of smaller, leaner teams—such as those behind independent AI research labs—as evidence that organizational agility is a greater asset than raw capital. For Google to regain its momentum, industry experts suggest it may need to undergo a structural shift, potentially separating its research-heavy AI units from its core advertising and search businesses to allow for faster decision-making and more focused resource allocation.
Future Outlook and Strategic Imperatives
Despite the recent sell-off and the challenges posed by competitors like OpenAI and Anthropic, Google retains immense structural advantages. It remains one of the few companies on earth with the data, the talent, and the liquid capital required to win a sustained, multi-decade technology war. The company’s ability to pivot its search product without destroying its primary revenue stream is the central challenge for CEO Sundar Pichai and his leadership team.
The path to recovery likely involves a transition from defensive spending to product-led growth. Investors are watching for signs of meaningful monetization from the AI stack—beyond simple cost-cutting or efficiency gains. Furthermore, the company faces mounting pressure from global regulators, particularly in the United States and the European Union, regarding its monopolistic practices in search and advertising technology.
As the industry moves into the next phase of the AI cycle, the "trust fund" narrative—that Google can simply outspend its way to victory—is being put to the ultimate test. The market is signaling that while scale is necessary, it is no longer sufficient to guarantee dominance in an era of rapid, disruptive innovation. For Google, the next 24 months will likely be defined by whether it can reconcile its status as an established titan with the need to once again act like a startup, prioritizing speed, developer engagement, and a sustainable, value-additive relationship with the global internet ecosystem.
