

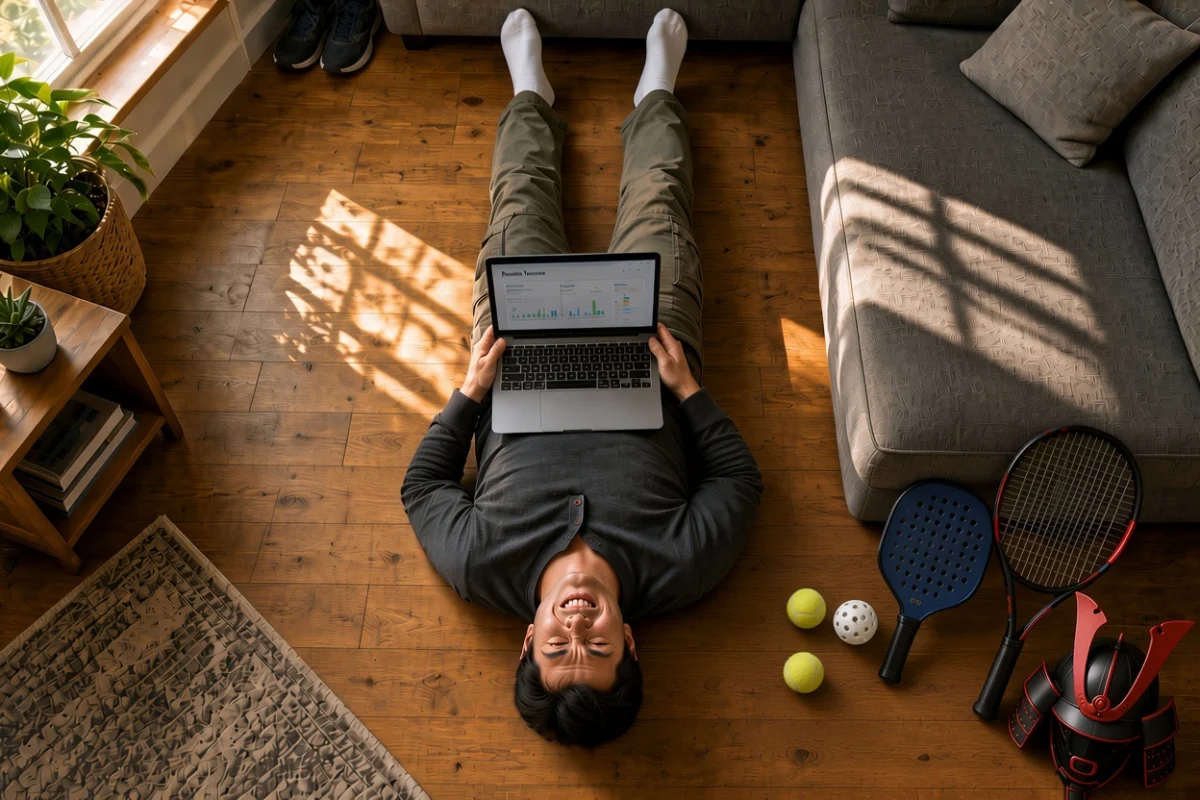
The intersection of physical health and financial stability is often overlooked by the workforce until a crisis forces a sudden, involuntary reassessment of personal risk management. Recent anecdotal evidence from high-earning professionals highlights a sobering reality: even those who have achieved significant financial milestones are not immune to the sudden onset of debilitating health conditions. When chronic respiratory issues or acute musculoskeletal injuries strike, the ability to generate income can evaporate in an instant, exposing the structural weaknesses in many personal financial plans.
A Chronology of Physical Decline and Productivity Loss
The recent experience of a professional struggling with chronic asthma and an acute spinal injury serves as a case study in the vulnerability of human capital. Earlier this year, the individual endured a two-week bout with a respiratory illness. For those with pre-existing conditions like asthma, such illnesses are rarely isolated incidents; they trigger a cascading effect where normal respiratory function is compromised, leading to prolonged recovery times and reduced cognitive and physical output.
In mid-August, this decline culminated in a series of events that hampered professional obligations. Despite feeling physically depleted, the individual attempted to fulfill a long-standing consulting commitment. The session lasted 75 minutes, with the speaker accounting for 80% of the duration. By the conclusion, their energy reserves were effectively exhausted, illustrating how even moderate professional engagement can become impossible under the strain of a physical disability.
Shortly thereafter, a severe back injury occurred, rendering the individual unable to perform basic movements. This was not an isolated incident but rather the result of a compounding series of stressors. The timeline of this physical collapse included:
- Sunday: High-intensity pickleball engagement lasting two hours, followed by instructional sessions.
- Monday: A 90-minute high-intensity tennis session.
- Tuesday: An aggressive weightlifting regimen, incorporating progressive loading and exceeding standard volume.
- Wednesday: A continued commitment to a morning physical routine despite early warning signs, resulting in a total loss of mobility.
The Statistical Reality of Disability
While catastrophic accidents—such as those involving heavy machinery or extreme sports—occupy the public imagination regarding disability, the data suggests a far more mundane, yet equally devastating, reality. According to the Social Security Administration (SSA), approximately 25% of 20-year-olds will experience a disability that keeps them out of the workforce for at least 12 months before reaching retirement age.
Furthermore, accidental injuries account for a mere 9% to 12% of long-term disability claims. Conversely, musculoskeletal disorders—including chronic back pain, degenerative joint disease, and related conditions—represent between 26% and 33% of all long-term disability claims. These figures underscore the fact that professional disability is more likely to be the result of cumulative physical wear and tear than a singular, dramatic event.
Understanding the Architecture of Disability Insurance
Financial advisors and human resources professionals emphasize that a failure to distinguish between the various forms of disability coverage is a primary cause of financial instability during medical crises.
Short-Term Disability (STD) is designed as a temporary bridge. It typically replaces 50% to 70% of an individual’s income, with an elimination period—the time between the onset of the disability and the commencement of benefits—often spanning only one to two weeks. STD is frequently provided as an employer-sponsored benefit or managed via state-run programs in jurisdictions such as California, Hawaii, and New York.
Long-Term Disability (LTD), however, is the critical safeguard for long-term solvency. LTD policies generally trigger after a 90-day elimination period and are designed to replace approximately 60% of income for years, or until the age of 65. The distinction between "own-occupation" coverage (which pays if you cannot perform your specific job) and "any-occupation" coverage (which pays only if you cannot perform any gainful employment) is a vital detail that many policyholders fail to scrutinize until it is too late.
Strategic Financial Mitigation
To insulate a household from the catastrophic loss of an income-earning member, financial experts suggest a multi-tiered approach to risk management.
1. Verification of Coverage
Employees should conduct an immediate audit of their HR-provided benefits. Many group policies feature monthly caps on payouts, which may leave high-income earners with a significant "coverage gap." Supplemental individual policies, particularly those with "own-occupation" riders, provide essential portability and broader protections.
2. The Emergency Fund as a Bridge
Given the elimination periods inherent in disability policies, a robust emergency fund is non-negotiable. While conventional wisdom suggests three to six months of expenses, those with dependents or self-employment income are advised to hold 12 months of liquidity in cash or ultra-short-term government securities. This capital serves as the bridge between the onset of an illness and the receipt of insurance benefits.
3. Diversification of Income Engines
The "single point of failure" model—relying entirely on one salary—is a high-risk strategy. Building multiple income streams, particularly those that are "asynchronous" or passive, provides a safety net. Side hustles that require physical presence, such as manual labor or in-person coaching, provide no protection against physical disability. Conversely, income derived from digital platforms, online courses, or passive investments remains functional regardless of the provider’s physical mobility.
4. Aggressive Early-Stage Capital Allocation
The peak earning years of an individual’s career typically coincide with their peak physical health. Experts recommend front-loading savings during this window. By maximizing tax-advantaged accounts such as 401(k)s and IRAs, and maintaining a high savings rate in taxable brokerage accounts, individuals lower their "burn rate." A paid-off mortgage or minimal fixed debt reduces the total income required to sustain a household, effectively acting as a form of self-insured protection.
The Broader Impact on Professional Sustainability
The implications of these findings extend to corporate culture and the broader economy. There is an increasing necessity for professionals to manage their health with the same rigor applied to their investment portfolios. The integration of preventive medicine—annual checkups, stress management, and appropriate physical conditioning—is a critical component of career longevity.
Moreover, the legal and estate planning side of the equation cannot be ignored. The establishment of a durable power of attorney and a clear healthcare directive ensures that, in the event of a total incapacity, the family’s financial and medical affairs can be managed without the delay of court intervention.
In conclusion, the transition from full-time productivity to disability is often a silent, gradual process rather than a sudden explosion. For those who view their health as a depreciating asset rather than a permanent fixture, the imperative is clear: optimize for resilience. By securing adequate insurance, maintaining sufficient liquidity, and diversifying income streams, individuals can build a professional life that withstands the inevitable physical challenges that accompany a long career.
