

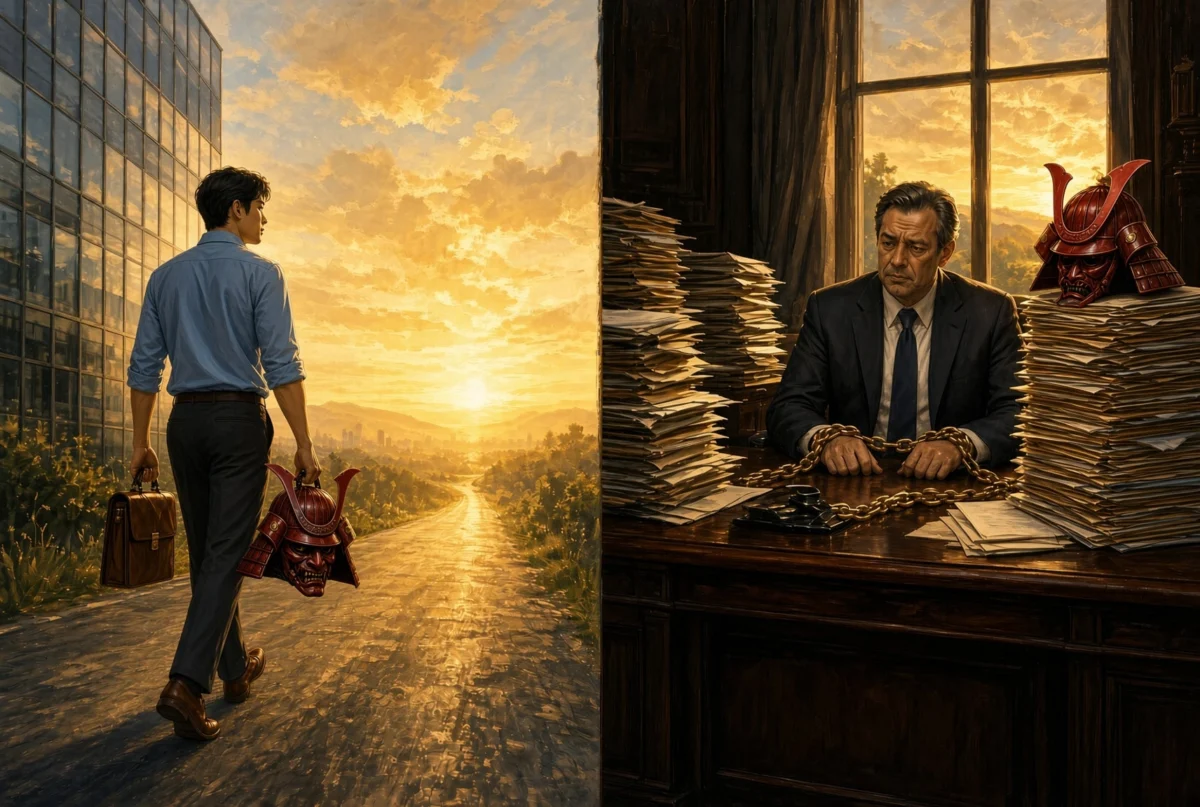
The concept of Financial Independence, Retire Early (FIRE) has transitioned from a fringe movement to a significant demographic trend over the last decade. While the movement emphasizes long-term fiscal discipline, a growing body of evidence suggests that the timing of early retirement is influenced more by external life variables and "golden handcuffs" than by raw asset accumulation. A comparative analysis of career trajectories reveals that individuals who exit the workforce in their mid-30s face significantly lower structural barriers than those who attempt to do so at 50.
The Dynamics of Early Career Exit
In 2012, at the age of 35, a segment of the professional workforce began testing the viability of "engineered layoffs"—the practice of negotiating severance packages rather than resigning. This period marked a shift in professional behavior, particularly in high-stress sectors like investment banking and technology. Data from the era indicated that professionals who departed at 35 often maintained higher levels of career mobility.
The primary factor distinguishing a 35-year-old from a 50-year-old retiree is the accumulation of fixed financial obligations. At 35, the average professional is less likely to be encumbered by the "lifestyle inflation" that defines the later stages of a high-earning career. This includes the mitigation of costs associated with private education, mortgage debt on primary residences, and the financial burden of multi-generational support, such as elder care for aging parents.
Chronology of the Golden Handcuffs
The "golden handcuffs" phenomenon—whereby high compensation and benefits packages prevent employees from leaving unsatisfactory roles—tends to tighten exponentially with tenure.
- Age 25–35 (The Accumulation Phase): Earnings are significant but generally lower than peak potential. Financial obligations are typically limited to personal debt or entry-level housing costs. The risk of career interruption is lower, as the job market remains receptive to candidates with a decade of experience.
- Age 35–45 (The Scaling Phase): Compensation often hits six or seven figures. Lifestyle expectations adjust upward, creating a higher "burn rate."
- Age 45–55 (The Peak/Retention Phase): Individuals in management roles often see total compensation (salary, bonuses, deferred equity) reach levels that make leaving financially daunting. During this period, the cost of replacing that income through personal investment returns requires a substantially larger capital base.
Comparative Economic Risks
Economic models show that the "failure rate" for early retirement is heavily influenced by the ability to re-enter the workforce. A study of labor market trends suggests that for professionals aged 35, the ability to return to a professional role within 12 to 24 months remains statistically high. Employers view a two-year hiatus from a 35-year-old candidate as a manageable career break, often citing personal development or entrepreneurial pursuits as a neutral or positive factor.
Conversely, for those at 50, the labor market presents a different set of challenges. Ageism, coupled with the rapid integration of artificial intelligence in knowledge-based industries, has compressed the demand for high-cost, mid-seniority labor. Consequently, a 50-year-old who retires is effectively "burning the boats." The decision is often binary: there is no path back to equivalent earnings, meaning the retirement must be permanent and fully self-funded.
Supporting Data and Market Realities
Financial analysts point to the "replacement rate" as the critical metric for FIRE success. For a 35-year-old, the portfolio must support a life for 50+ years, but the individual retains the "human capital" option—the ability to earn income if market conditions sour. For a 50-year-old, the portfolio must support roughly 35 years, but the human capital option is largely exhausted.

Moreover, the inflationary pressure on major expenditures—specifically private education and healthcare—has altered the landscape for the 50-year-old demographic. University tuition costs, which have outpaced the Consumer Price Index (CPI) for decades, represent a massive capital drain that was not a factor for the 35-year-old cohort of the early 2010s.
The Psychological Component of Retirement
Beyond the balance sheet, there is a distinct psychological shift. Younger retirees often possess a higher capacity for "re-skilling" and adaptation. At 50, the professional identity is frequently tied to the organizational hierarchy. The loss of that status, combined with the pressure to fund generational wealth transfers for children entering an increasingly competitive, AI-driven job market, creates a significant barrier to exit.
Industry experts note that the most successful transitions often involve a "trial period." A sabbatical of three to six months is widely considered the minimum duration required to gauge whether an individual can manage the psychological transition from a structured work environment to a self-directed one.
Implications for Future Workforce Trends
The trend toward early retirement is unlikely to abate, but its nature is shifting. We are observing a rise in the number of individuals who are not "retiring" in the traditional sense, but rather shifting to non-traditional work. This includes part-time consulting, contract work, or roles in the gig economy that provide supplemental income without the 60-hour-per-week commitment of traditional corporate finance or tech roles.
However, the consensus among financial advisors remains clear: the math heavily favors an earlier departure. When an individual waits until 50 to retire, they are often trading the "golden years" of their prime for a level of security that may already have been achievable at 35. The risk of failure is significantly mitigated by youth and the ability to pivot, whereas the risk of staying in a high-paying but soul-draining role is the permanent loss of time that cannot be recovered.
Strategic Exit Planning
For those considering an exit from the workforce, the focus has shifted from simple resignation to strategic negotiation. The "engineer your layoff" approach—which involves leveraging performance metrics and mutual separation agreements to secure severance—has become a standard recommendation for professionals in the corporate sector. By treating the departure as a business transaction rather than a personal decision, employees can often secure the necessary runway to bridge the gap between active employment and long-term financial independence.
In conclusion, while the allure of the "peak earning year" at 50 is powerful, the structural risks—job market volatility, the rapid evolution of technology, and the heavy weight of family responsibilities—suggest that the window for a truly flexible and resilient retirement is significantly wider in one’s 30s. The decision to retire is rarely about having "enough" money; it is about the threshold at which the cost of staying in the workforce outweighs the security of leaving it. As the economic landscape continues to evolve, the ability to exit early, while the cost of failure is still manageable, may become the most important financial advantage a professional can possess.
